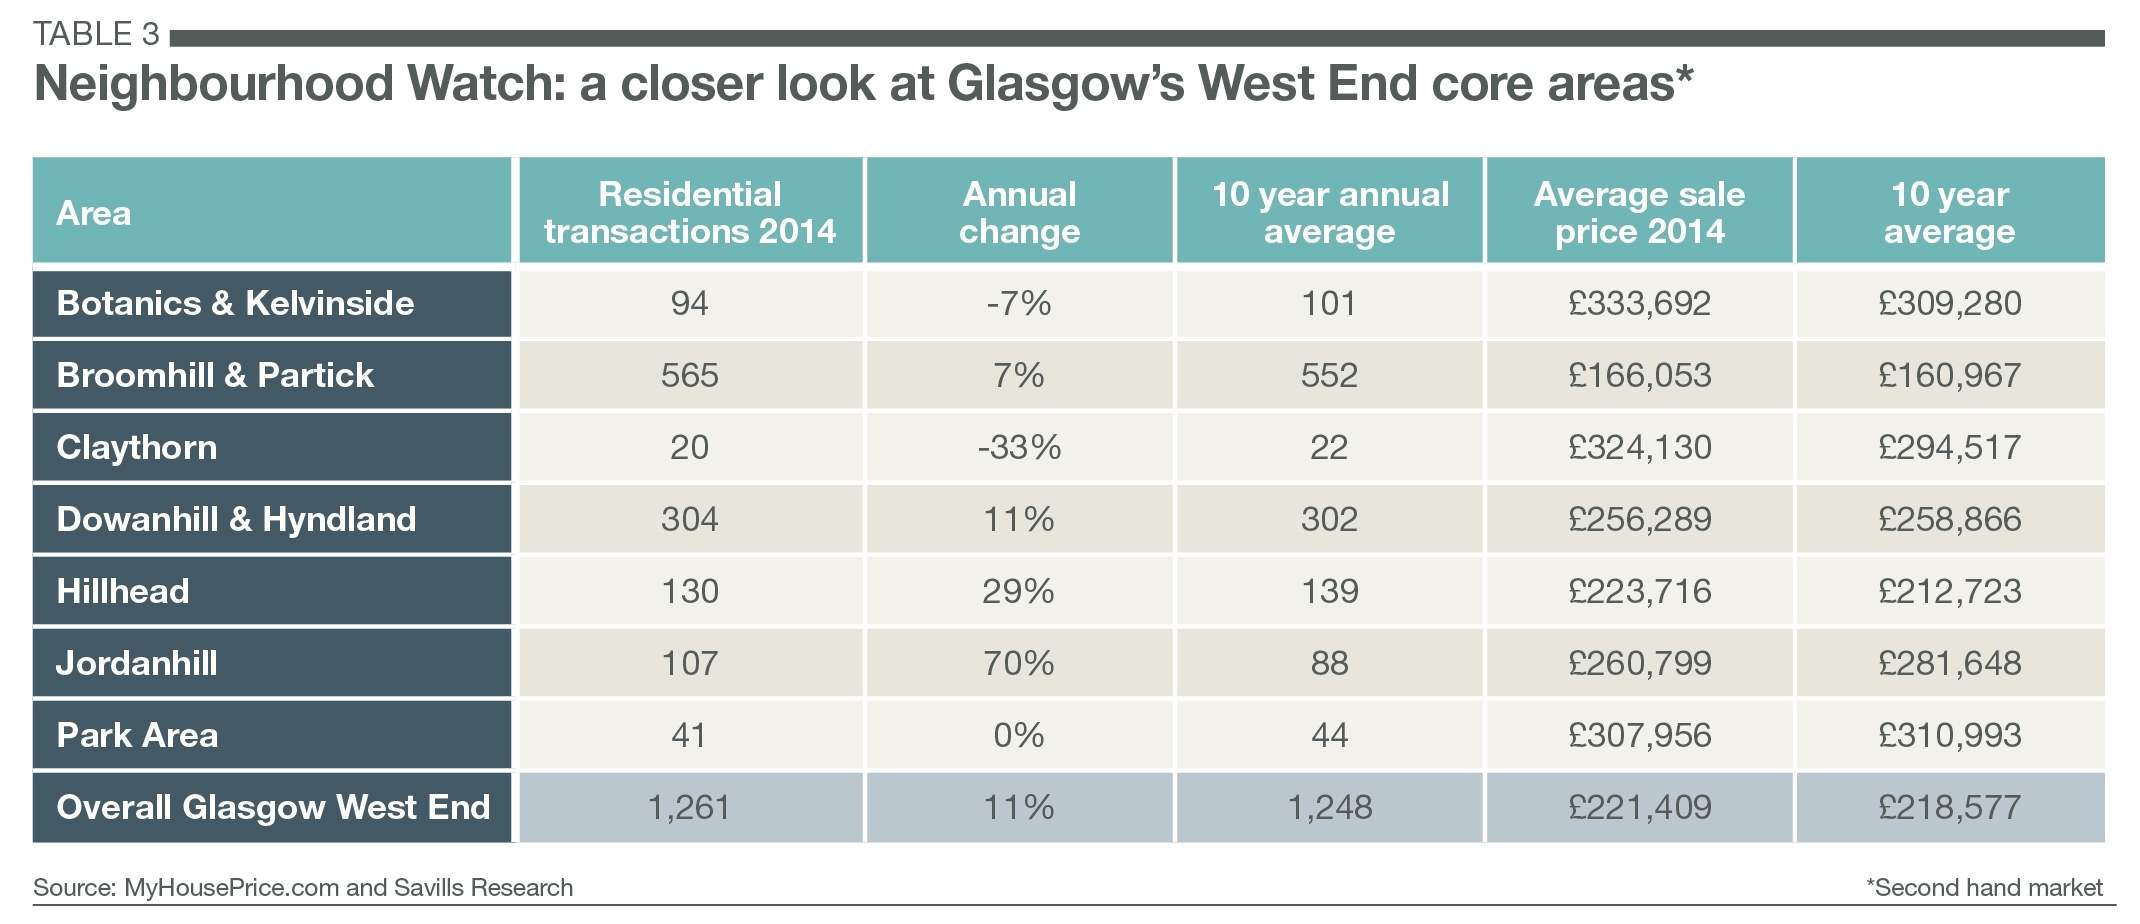
The residential market across Scotland has been supported by ‘local heroes’ over the past two years, property hotspots which are primarily located in the core central locations of the Scottish hubs of Aberdeen, Edinburgh and Glasgow. One such local hero is Glasgow’s West End where the residential market has outperformed the region in terms of average prices.
Our research shows that the average sale price across the West End (defined as Park, Hillhead, Dowanhill, Hyndland, Kelvinside, Claythorn, Jordanhill, Broomhill and Partick) reached £221,409 during 2014. This was 69% higher than the average sale price across the Glasgow City Local Authority area as a whole over the same period.
There was also an 11% increase in the number of transactions, reaching 1,261 sales last year. The number of sales across the Glasgow City Local Authority area as a whole is currently 13% below the 10 year average. However, the residential activity across Glasgow’s West End is 1% higher than the 10 year average.
The majority of sales across the West End take place below £200,000, making up 58% of residential transactions in 2014. At the top end of the market, there were fewer sales in the West End than one might expect, with 9% of activity taking place last year above £400,000.
The market is increasingly being driven by younger professionals aged from 30 to 39, comprising around 41% of Savills sales last year. This target market had been somewhat subdued following the housing market downturn, mainly due to lending constraints. However, there was pent-up demand among this age category aspiring to upsize. This latent demand, coupled with improved lending, has led to an increase in activity among this age group, following low levels of sales during 2011 and 2012.
Looking ahead, we expect transactions across Glasgow’s West End to grow in line with Scotland as a whole, supported by low mortgage rates and a gently improving economy.
We expect residential values across the core areas of Glasgow’s West End to continue their positive upward trend, with growth of around 20% expected over the next five years, supported by favourable rates of LBTT.