■ Improving operational performance and investor sentiment is fuelling appetite for hotel assets. In contrast to the past two years, which were dominated by distressed sellers, we are now seeing the rise of the 'distressed buyer' who is increasingly eager to spend their allocated funds. This combined with a lack of stock and competition for prime assets is leading many investors to look beyond London.
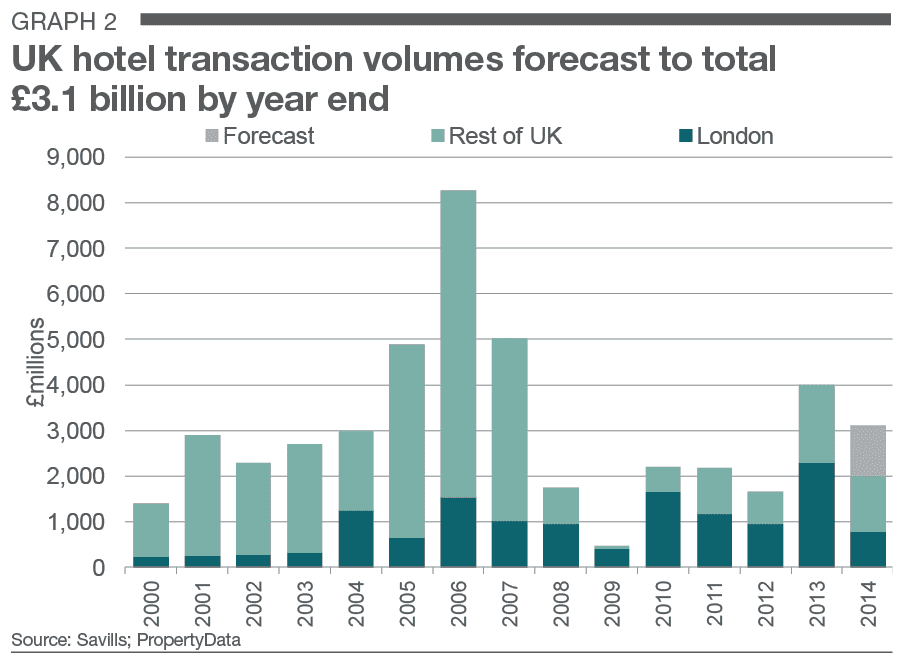
■ This movement of investors beyond the Capital is apparent in the regional share of total transactions and the profile of buyers. Regional 2014 volumes to date account for 62% of total UK transactions whereas in 2013 its share was 44%. Also, institutional investors have become more acquisitive in the regions this year with transaction volumes up 135% on the same period in 2013.
■ However, despite the increasing willingness of investors to look beyond London sourcing stock remains an issue. It was expected that more single assets would be sold out of last year's portfolio deals, but this did not materialise. As a result total UK transaction volumes to date for 2014 are 11.5% down on the same period last year totalling £2 billion.
■ Stock issues have also been exacerbated by the decline in receivership assets coming to the market, partly helped by the improvement in operational conditions. This has resulted in an 87% fall in sales volumes by banks/receivers compared to full year 2013.
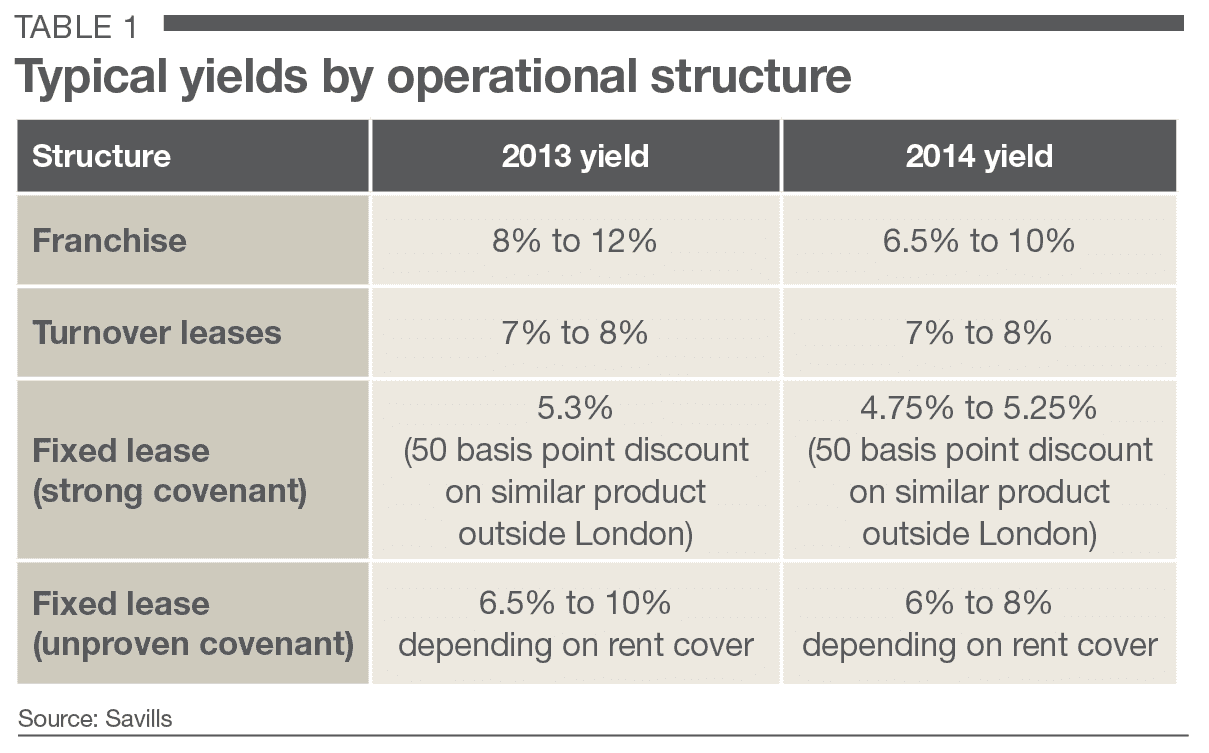
■ This lack of stock combined with improved investor demand and confidence in the sector has meant that yields have compressed over the first half of the year. Continued constraints in pipeline may apply additional yield pressure going forward.